Commercial Auto Insurance in Miami: Florida Requirements and Cost
Commercial auto insurance in Miami starts with the same base every Florida vehicle needs, PIP and property damage, and then climbs fast with truck weight, who drives and what you haul. Miami-Dade traffic doesn’t help the price either.
This guide covers what Florida law requires for business vehicles, what commercial auto insurance costs in Florida and in Miami, how to keep the bill down, and when a box truck or van needs more than the minimum.
Do you need commercial auto insurance in Miami?
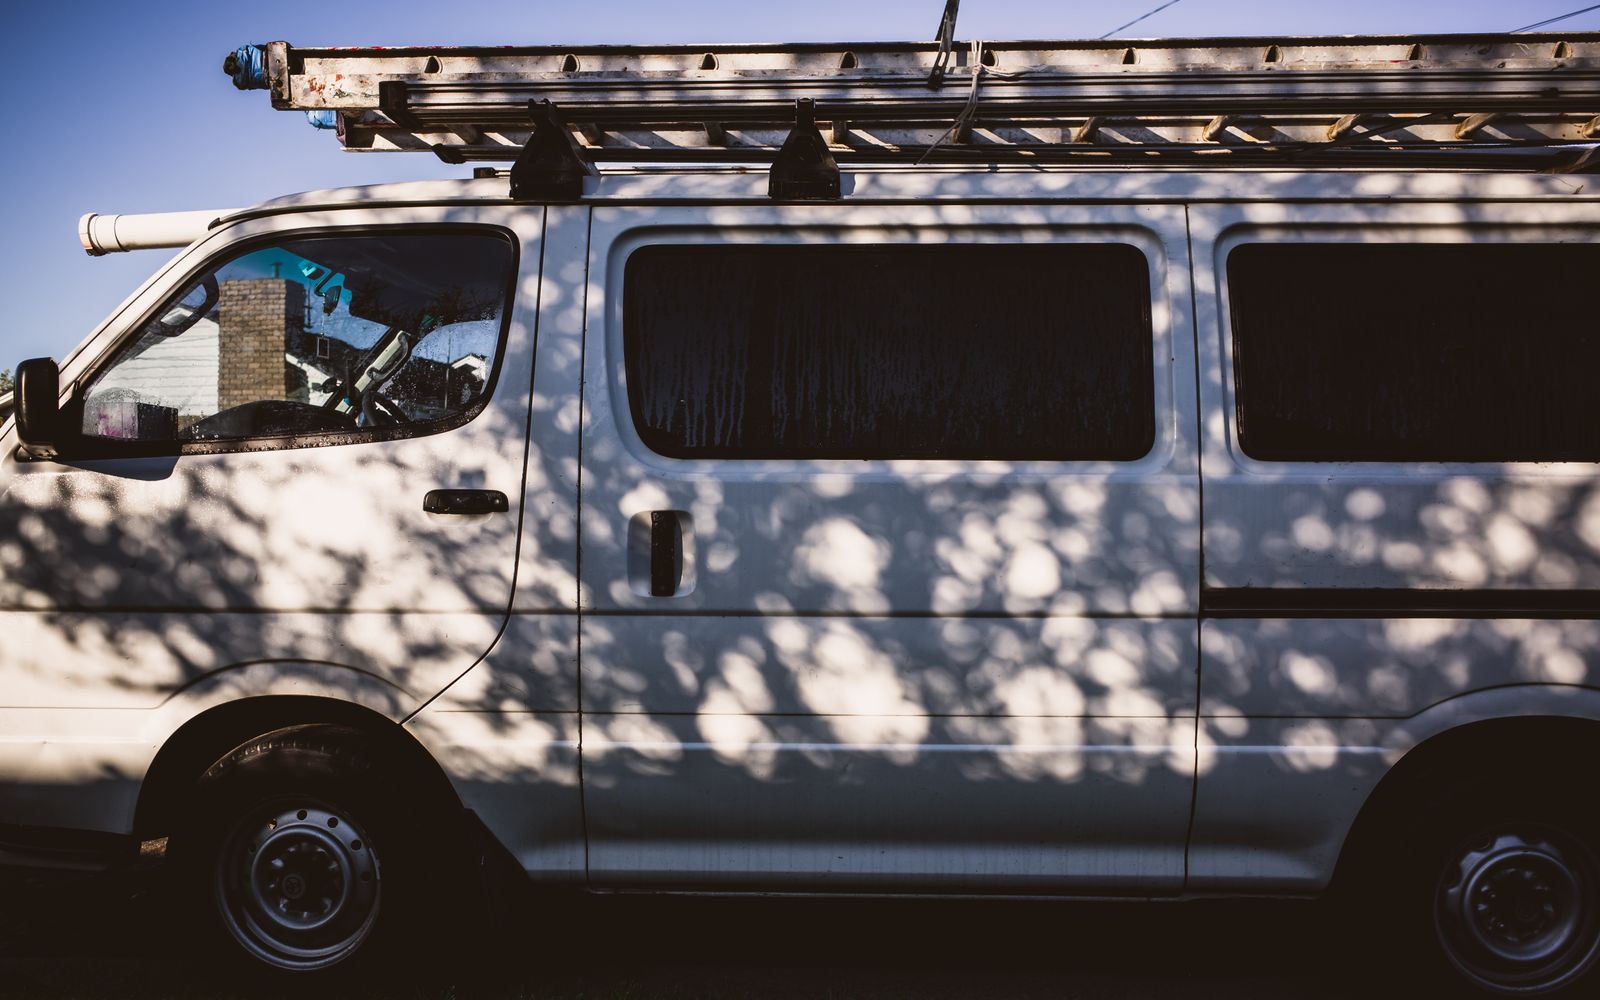
Picture a plumber’s white van with a ladder rack, parked outside a job on Bird Road. It’s registered to the business, it carries $4,000 in tools, and his helper drives it to the supply house twice a day. That van has three separate reasons to be on a commercial policy.
You need commercial coverage if any of these is true:
- The vehicle is titled or leased to the business. An LLC-owned truck usually can’t go on a personal policy.
- It’s used mainly for work. Florida’s no-fault law treats a pickup, panel truck or van “used primarily for occupational, professional, or business purposes” as a commercial vehicle (section 627.732).
- Employees drive it. Every one of them is a driver your insurer needs to know about.
- It hauls tools, equipment or other people’s goods, or it’s a box truck, dump truck or anything with a lift gate.
Commuting and the occasional bank run usually stay personal. Daily job sites and deliveries are where personal policies start denying claims, which is an ugly thing to learn on the shoulder of the Palmetto. And a business owner’s policy doesn’t cover vehicles at all. Commercial auto is always its own policy.
Florida commercial auto insurance requirements by truck weight
| Vehicle | Florida minimum liability (per occurrence) | Where it comes from |
|---|---|---|
| Cars, pickups, vans and light trucks under 26,000 lbs | $10,000 PIP + $10,000 property damage | F.S. 627.733, 627.736, 324.022 |
| 26,000 to 34,999 lbs | $50,000 combined bodily injury and property damage, on top of the base | F.S. 627.7415(1) |
| 35,000 to 43,999 lbs | $100,000 combined | F.S. 627.7415(2) |
| 44,000 lbs and up | $300,000 combined | F.S. 627.7415(3) |
| Any truck covered by federal rules (49 CFR 387) | The federal minimum for that operation | F.S. 627.7415(4) |
Trucks over 10,001 pounds that haul across state lines also fall under federal rules. For-hire general freight carriers need at least $750,000 of liability, and hazardous loads need $1 million to $5 million (49 CFR 387.9). Staying in Florida doesn’t fully exempt a heavy truck: the state applies most federal safety rules to in-state trucks of 26,001 pounds and up (section 316.302). If you’re not sure which bucket your truck is in, ask before you take the load.
How much does commercial auto insurance cost in Miami?
Two estimates published in 2026 give a useful Florida range. Industry modeling of five major carriers puts the average Florida business at about $230 a month ($2,763 a year) for minimum coverage. Policy data from a national small-business insurance marketplace puts its typical Florida customer at about $412 a month ($4,943 a year). The gap is mostly coverage: bare minimums on one end, the limits real businesses buy on the other.
Expect Miami to sit toward the higher end. Carriers price by where the vehicle is garaged, and big, congested cities with more claims cost more than small towns. Treat all of these as market estimates, not a quote. Your drivers, vehicles and work decide your real number.
Florida’s 2023 tort reform law, HB 837, was aimed at the lawsuit costs behind those prices. It cut the window to file most negligence suits from four years to two (s. 95.11) and generally bars anyone more than 50 percent at fault from collecting (s. 768.81). How much of that reaches your premium depends on the carrier.
How to get cheap commercial auto insurance in Miami (without getting burned)
Cheap commercial auto insurance in Miami means the right limits at the best price, not the lowest number on a quote that won’t pay a claim. What actually moves the price:
- Clean drivers. Pull motor vehicle records before anyone gets the keys. One driver with recent tickets can raise the whole policy.
- Honest radius and garaging. Report where the truck sleeps and how far it goes. Accurate is cheaper than a surprise at audit time.
- Higher physical damage deductibles on older vehicles you could afford to fix yourself.
- Safety discounts. Some carriers credit dash cams, telematics or a written safety program.
- Shopping every renewal. Pricing swings between carriers year to year, which is the whole point of an independent agent.
Commercial truck insurance in Miami: box trucks, vans and small fleets
Box trucks are where Miami businesses most often get the coverage wrong. One box truck might weigh 14,000 pounds and another 30,000, and crossing 26,000 pounds jumps the legal minimum from $10,000 of property damage to $50,000 of combined liability. Know your truck’s weight rating before you shop.
Two add-ons matter for almost every Miami work vehicle. Hired and non-owned auto covers your business when an employee runs an errand in their own car or you rent a truck, because the injured person’s lawyer will look at who sent them. And tools and cargo are often not covered by the auto policy itself, so a van full of equipment usually needs an inland marine or tools policy too. If your drivers are employees, you likely need workers’ comp as well, since an on-the-clock crash is usually a workers’ comp claim.
Why use a local commercial auto insurance agent in Miami
A captive agent can only quote one company. Insurance For Life is an independent agency in Miami, so we compare multiple carriers for the same truck and tell you which one actually fits the work you do. That matters most for the hard cases: new businesses, drivers with a ticket or two, heavy trucks and anything that crosses state lines.
We also handle the rest of your commercial insurance in Miami, from general liability to workers’ comp, so your auto limits and your contracts line up. Call (786) 332-5602 or request a quote below.
Frequently asked questions
Does Florida require commercial auto insurance?
Every vehicle registered in Florida needs at least PIP and property damage liability, including business vehicles. Commercial trucks of 26,000 pounds or more also need $50,000 to $300,000 of combined liability depending on weight, and interstate carriers must meet federal minimums.
Does commercial auto insurance cover personal use?
Usually, yes. A commercial policy generally covers the listed vehicle when a permitted driver uses it, including a stop at the grocery store on the way home. Rules on who may drive it vary by carrier, so if employees take vehicles home, tell us and we’ll make sure the policy says so.
How much commercial auto insurance do I need?
More than the state minimum. Start with what your contracts require: general contractors, property managers and shippers commonly ask subs for a $1,000,000 combined single limit. Interstate for-hire carriers can’t go below the federal $750,000 floor.
Do I need a USDOT number if I only drive in Florida?
USDOT registration is triggered mainly by interstate commerce. Florida applies many of the same safety rules to in-state trucks of 26,001 pounds or more, so if you run a heavy truck, check with FMCSA or ask us before assuming you’re exempt.
Get your Miami work trucks covered properly
Tell us what you drive, who drives it and what you haul, and we’ll compare commercial auto insurance in Miami across multiple carriers. Call (786) 332-5602.
Sources: Florida Statutes sections 627.7415, 627.732, 627.733, 627.736, 324.021, 324.022 and 316.302; Code of Federal Regulations, 49 CFR Part 387 (sections 387.7 and 387.9) and 49 CFR 390.5 and 390.201; Florida Statutes 95.11 and 768.81 and HB 837 (2023); cost estimates from MoneyGeek (Florida commercial auto cost analysis, updated October 15, 2026) and Insureon customer data (Florida commercial auto cost page, updated March 19, 2026). This article is general information, not legal advice. Coverage depends on the policy and carrier, and rules change, so confirm your situation with a licensed agent.